The Reff & Associates | Deloitte Legal tax litigation team secured, for an individual taxpayer, a court stay of enforcement of ex officio tax assessments through which the tax authority had established tax liabilities of approximately RON 1.2 million. The assessments concerned investment income and were issued following a procedure to estimate the taxpayer’s income.
The court’s ruling is significant beyond the taxpayer’s individual circumstances, as it highlights an issue increasingly encountered in practice: the limits within which the tax administration may assess tax liabilities ex officio based on financial information automatically received from other countries or financial institutions.
This procedure is necessary when a taxpayer fails to fulfil filing obligations, but it does not allow every reported amount to be treated as taxable income. Financial data must be understood in context, verified and reconciled with the economic reality of the transactions.
In the case examined by the court, the key issue was the fundamental difference between the turnover of an investment account and the investor’s actual gain. However, determining the actual outcome requires consideration of, among other factors, the acquisition cost of the assets, the losses incurred and the expenses associated with the transactions, rather than simply the total value of sales.
The stay of enforcement was primarily supported by the tax assessments’ failure to explain clearly and verifiably how the tax authority had calculated the taxable base. Financial records revealed substantial discrepancies between gross transaction values and actual results, suggesting that the estimate relied on account turnover or gross receipts without accounting for acquisition costs or the transactions’ economic outcome. The suspension does not constitute a final annulment of the assessments; their legality remains subject to review through the appropriate procedures. In the meantime, it shields the taxpayer from the immediate effects of enforcing tax liabilities whose basis has been seriously questioned.
“The ruling is important because it shows that ex officio tax assessment is neither a mechanism without limits nor a procedure that can operate solely based on automated correlations between data. The tax authority has an obligation to explain what information it used, how it interpreted that information and the reasoning by which it arrived at the amount allegedly due. The more indirect the method used, the greater the need for transparency and justification. The digitalisation of tax administration and information exchange are necessary developments. They enable faster identification of situations requiring verification. However, technology and large volumes of data cannot replace the legal and economic analysis of each case. Automatically reported information is a starting point for verification, not a definitive conclusion as to the existence and amount of taxable income,” said Ștefan Mihărtescu, Senior Managing Associate, Reff & Associates | Deloitte Legal.
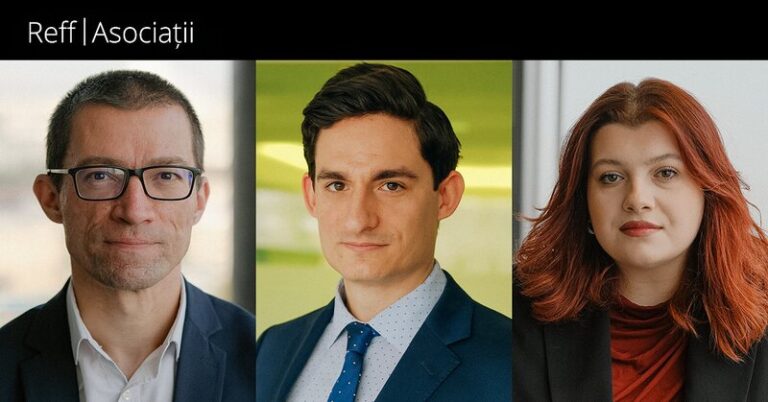
The Reff & Asociații | Deloitte Legal team that advised and represented the taxpayer in this litigation was led by Bogdan Marculet, Counsel, and included Stefan Mihartescu, Senior Managing Associate, and Diana Bicioc, Associate.